02 · Hail & insurance
When it hails, your claim comes down to a chalk square.
Denver sits in the busiest hail corridor in the country. Here is exactly what happens between the storm and the second check — and the four things a roofer should tell you that most don’t.
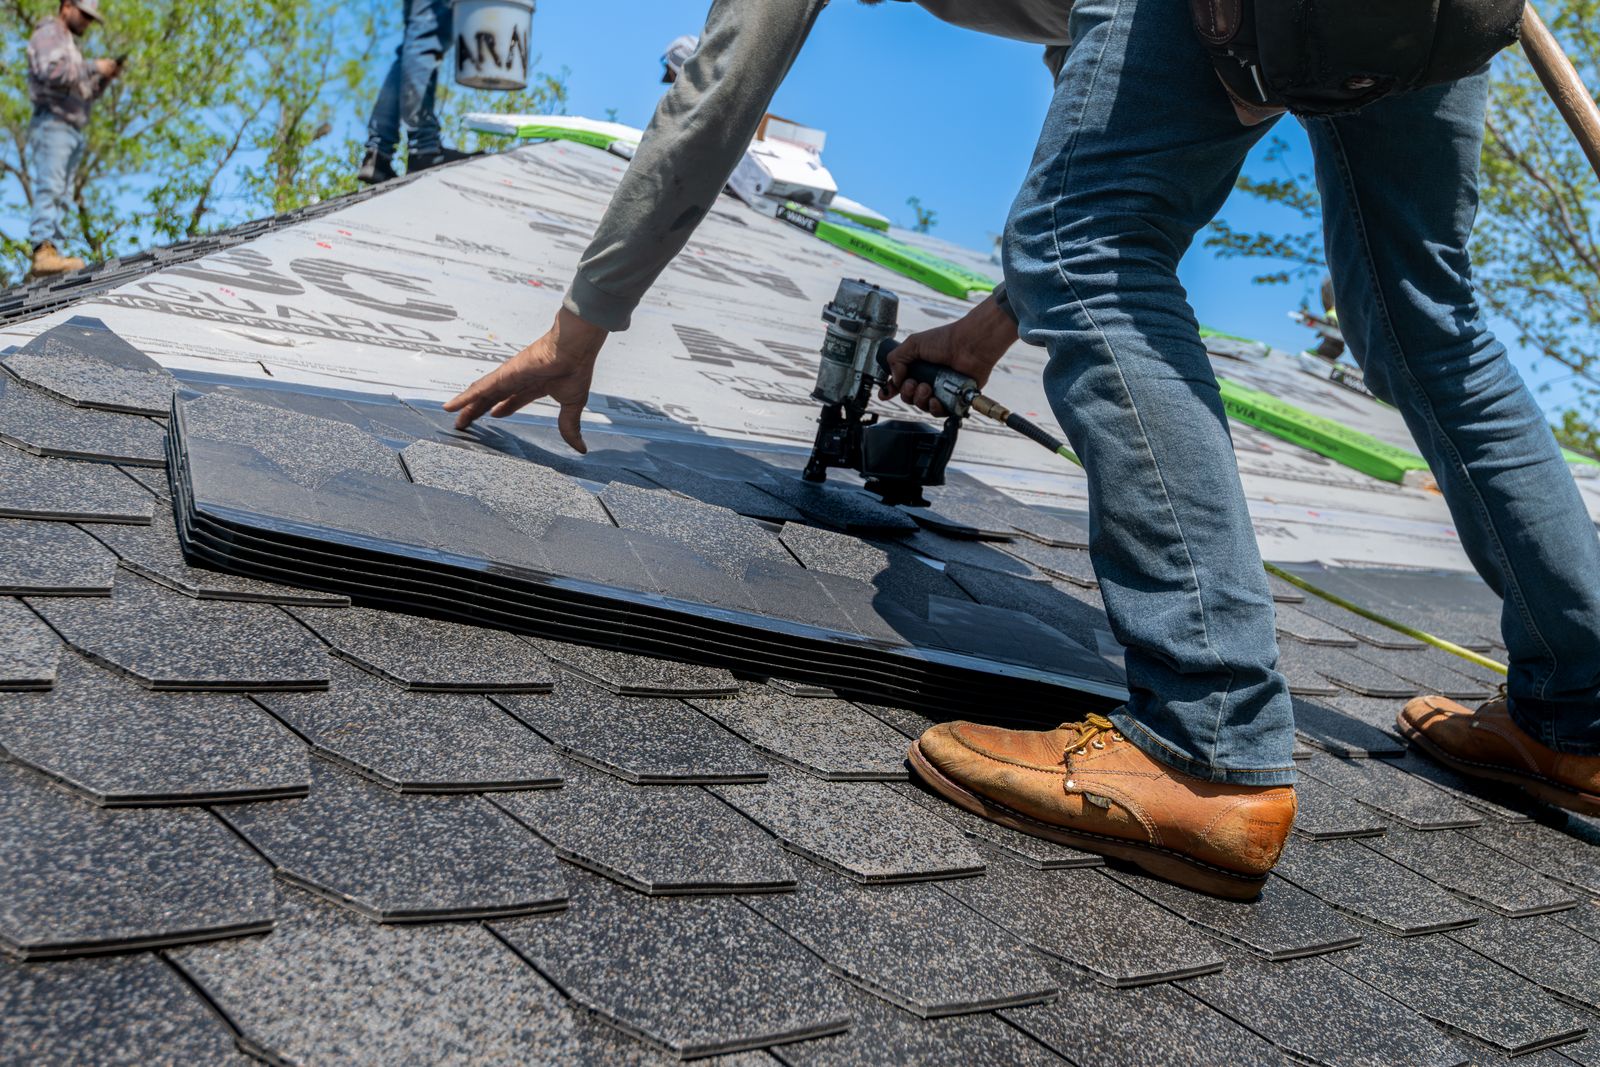
Your adjuster will chalk a ten-foot square on each slope and count the hail hits inside it. Above a threshold, the carrier replaces the slope. Below it, they don’t. That square decides whether you get a new roof or a letter.
So we chalk it first. Every slope — photographed, counted and dated before the adjuster arrives — and then we stand on the roof with them and walk the squares together. The difference between a paid claim and a denied one is usually the person up there holding the chalk.
How a hail claim actually works.
Nine steps, in the order they happen. Most of them are yours, not ours, and we’ll tell you which.
It hails.
Front Range hail season runs roughly May through August. A one-inch stone doesn’t put a hole in a shingle — it bruises it, knocking the granules loose and fracturing the mat underneath. The bruise is invisible from the ground and starts leaking a few years later.
Get it looked at by someone you called.
Not by the truck that knocked. Anyone who wants to inspect your roof should be someone you phoned, and they should hand you photographs of what they found whether or not you hire them.
The chalk.
We chalk a ten-by-ten test square on every slope, circle each hit, count them, photograph and date it. We also check the soft metals — the vents, the gutters, the air-conditioner fins, the mailbox — because dented metal is how an adjuster confirms the storm was real and how big it was.
You file the claim.
You, not us. In Colorado a roofer can’t act as your adjuster, and we wouldn’t want to. We give you the photos, the counts and the date, and you make one phone call to your carrier. If you’d like, Marisol will sit with you while you do it.
The adjuster meeting.
Your carrier sends an adjuster to walk the roof. We’re on it with them. We walk the squares together, hit by hit. Most disagreements about a hail claim happen on the roof that day, and they get settled by who’s up there and what they can point at.
The scope, ACV and RCV.
The adjuster’s report is a scope: what they’ll pay for, line by line. If your policy is replacement-cost, the first check is the actual cash value — replacement cost minus depreciation for the roof’s age. The depreciation is released after the work is done. We show you both numbers before you sign anything.
The supplement.
First scopes miss things: the ice-and-water shield the code requires, drip edge, the extra hours a steep roof takes. We write the supplement with photographs and the code reference, and your carrier reviews it. That’s normal, not a fight.
The build.
One day, for most houses. Same crew, same photographs, same walk-through. The whole day, hour by hour.
The second check.
We invoice your carrier for the released depreciation so you’re not chasing it. On a covered claim, what you pay is your deductible and the cost of anything you chose to upgrade beyond the scope — a Class 4 shingle, say. Nothing else.
If it hailed last night.
Six things, in this order. None of them involve signing anything.
- Photograph the yard. Hail on the ground next to a coin or a tape, the dents in the gutters, the car, the top of the air-conditioner. It melts by nine.
- Stay off the roof. Bruised shingles are slick, and you can’t see a hit from up there anyway.
- Don’t sign anything today. Not an inspection agreement, not a “contingency”, not an assignment of your claim. Nothing you’re handed on your porch after a storm is urgent.
- Call your agent, not the claim line. Ask how long you have to file — it’s often a year — and whether your policy is replacement-cost or actual-cash-value. You want to know both before you start.
- Get it looked at by someone you called. Us, or anyone else — but someone with a yard in this city and a phone number that’s been the same for a while.
- Read any contract for one line. That you can cancel within 72 hours if the claim is denied. Colorado law requires it. If it isn’t there, that tells you something.
Out-of-state plates. Magnetic signs on the truck door. An offer to “take care of” your deductible. A contract that assigns your claim to them. A crew nobody at the company has met. Any one of these is enough.
- 01
Your deductible is yours.
Colorado’s residential roofing law (SB 12-038) makes it illegal for a roofer to pay, waive or rebate your insurance deductible. If someone at your door offers to, that tells you what you need to know about them.
- 02
If the claim is denied, you can walk.
The same law gives you 72 hours after a denial to cancel a roofing contract and get your deposit back. It’s in our contract in plain language, on page one.
- 03
We never take over your claim.
Some contracts assign your insurance benefits to the roofer, so the checks go to them and the decisions do too. Ours doesn’t. The claim is yours, the checks are yours, and you pay us when the work is done.
- 04
We don’t knock after a storm.
If it hailed last night, we’re on our own customers’ roofs today, not on your porch. Call when you’re ready. The square will still be there.
Straight answers.
Will filing a hail claim raise my premium?
In Colorado, a claim for weather damage is generally treated differently from a claim you caused, and hail is the most common claim in the state. Your rate is far more likely to move because of what the whole neighborhood filed than because of what you did. Ask your agent — they’ll tell you how your carrier handles it.
The adjuster said the damage is “cosmetic”. Now what?
Ask for the test-square counts and the photographs, slope by slope. If ours show hits theirs don’t, we’ll request a re-inspection and be on the roof for it. Sometimes the adjuster is right and the roof has a few more years in it — we’ll tell you that too.
Can I upgrade to a Class 4 shingle on a claim?
Yes. The carrier pays for a like-for-like roof; the difference for an impact-rated shingle is yours. Many Colorado insurers then reduce your premium for it, which can pay the difference back over a few years. More on Class 4.
Had hail? Call when you’re ready.
We’ll chalk it, photograph it and hand you the counts — whether or not you hire us for the roof.